Paying RM195 a year just to keep a card in your wallet?
What if the card paid you back instead, with zero annual fee for life?
This guide reveals the best no annual fee credit cards in Malaysia, ranked by real savings potential. Whether you’re a fresh grad, a weekend shopper, or someone who simply hates fees, the right card can give you cashback or rewards without a single ringgit in annual fees.
Last checked 16 November 2026 against RinggitPlus card listings. Card terms change often, so always confirm the latest rates, caps and fees on the bank’s website before you apply. Disclosure: we may earn a commission if you apply through links on this page, at no extra cost to you.
What Is a No Annual Fee Credit Card?
A no annual fee credit card means the bank doesn’t charge you a yearly fee to keep the card. In Malaysia, you’ll see two types:
- Free for life (no annual fee, ever, as listed by RinggitPlus).
- Free with conditions (the fee is waived only for the first year, or only if you hit a spend or swipe target).
This guide only covers free-for-life cards. No waiver targets, no tricks.
Example: A card with a RM195 annual fee costs you RM975 over five years before it earns you a single sen. A free-for-life card costs you RM0 in annual fees.
Heads-up: “free” isn’t always zero. RinggitPlus lists a RM25 service tax on each principal and supplementary card, charged on activation and every anniversary. That’s RM125 over five years, which is still far cheaper than a fee card.
Top 9 No Annual Fee Credit Cards in Malaysia
| Rank | Credit Card | Why It’s a Good Pick | Cashback / Points | Cap | Min Income | Annual Fee | Apply |
|---|---|---|---|---|---|---|---|
| 1 | CIMB Cash Rebate Platinum | Simple everyday cashback on petrol, groceries and bills | 5% with RM3,000+ eligible spend, 2% below | RM30 | RM2,000 | Free for life | 🔗 Apply |
| 2 | BSN Visa Cash Back | Free for life with no conditions | Up to 5% on groceries, dining and petrol with RM3,000+ monthly spend | RM15 | RM4,000 | Free for life | 🔗 Apply |
| 3 | Maybank 2 Gold Cards | Weekend cashback on all spending, local and overseas | 5% on weekends (Amex card) | RM50 | RM2,500 | Free for life | 🔗 Apply |
| 4 | CIMB PETRONAS Visa Platinum-i | Shariah-compliant fuel cashback | 8% at PETRONAS with RM2,000+ statement balance (4% from RM500) | RM50 | RM2,000 | Free for life | 🔗 Apply |
| 5 | RHB World Mastercard | Cashback plus lounge access, no annual fee | Up to 6% on local travel, petrol and dining with RM3,500+ monthly spend | RM30 | RM6,667 | Free for life | 🔗 Apply |
| 6 | Maybank Islamic PETRONAS Ikhwan Visa Platinum-i | Shariah-compliant weekend petrol cashback | 8% at PETRONAS on weekends, 1% on weekdays | RM50 | RM5,000 | Free for life | 🔗 Apply |
| 7 | Public Bank Quantum Visa | Easy cashback for tap-and-go spenders | 1% on contactless payments of RM100+ | RM20 | RM3,000 | Free for life | 🔗 Apply |
| 8 | Alliance Bank Visa Virtual | Online and e-wallet rewards | 8x points on online shopping and e-wallet reloads | RM3,000 spend per category | RM2,000 | Free for life | 🔗 Apply |
| 9 | UOB Simple Card | Interest rebate, not a rewards card | 10% cashback on finance charges when you pay the minimum on time | No cap | RM2,000 | Free for life | 🔗 Apply |
In-Depth Reviews of the Top Picks
1. CIMB Cash Rebate Platinum
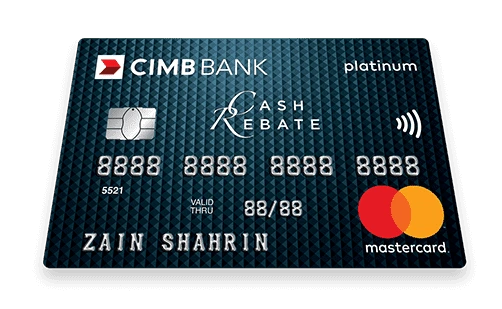
Best For: Everyday spenders who want one simple, fee-free cashback card
Why It’s Great: Up to 5% cash rebate on petrol, groceries, cinema, mobile and utility bills once your eligible spend reaches RM3,000 a month (2% below that). Everything else earns 0.2%. No annual fee for life.
Heads-Up: Capped at RM30 per month, and mobile and utility bills must be paid by standing instruction to count.
🔗 Apply
2. BSN Visa Cash Back
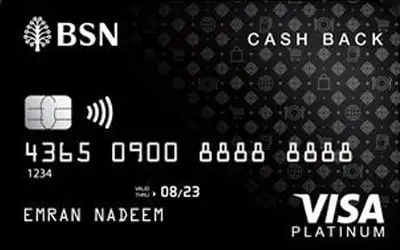
Best For: Budget-conscious Malaysians who want a card with no fee and no conditions
Why It’s Great: Free for life without any condition. Earn up to 5% cashback on groceries, dining and petrol when you spend RM3,000+ a month, plus 1% unlimited cashback on overseas spend.
Heads-Up: Groceries, dining and petrol are capped at RM15 per month, and you earn only 1% from RM1,000 spend (0.2% below that). Minimum income is RM4,000/month.
🔗 Apply
3. Maybank 2 Gold Cards
Best For: Weekend shoppers and diners
Why It’s Great: You get two cards (an American Express plus a Mastercard or Visa), both with no annual fee for life. Spend any amount on weekends and earn 5% cashback on local or overseas spending with the Amex card.
Heads-Up: Cashback is capped at RM50 per month and applies to the Maybank 2 American Express card only.
🔗 Apply
4. CIMB PETRONAS Visa Platinum-i
Best For: PETRONAS drivers who want a Shariah-compliant card
Why It’s Great: 8% cashback on PETRONAS, Setel app and EV charging at PETRONAS stations when your statement balance hits RM2,000 (4% from RM500). Groceries, dining and cashless parking earn 2% at RM2,000+ (1% from RM500).
Heads-Up: Cashback is capped at RM50 per statement cycle, and the rate halves if your monthly spend stays under RM2,000.
🔗 Apply
5. RHB World Mastercard
Best For: Light travellers who want lounge access without paying a fee
Why It’s Great: Up to 6% cashback on local travel, petrol and dining once you spend RM3,500+ a month (1% from RM1,000, 2% from RM2,500). You also get up to 6 free Plaza Premium Lounge visits in Malaysia and RM600,000 travel insurance.
Heads-Up: Cashback is capped at RM30 per month, and you need RM6,666.67 monthly income.
🔗 Apply
6. Maybank Islamic PETRONAS Ikhwan Visa Platinum-i
Best For: Shariah-compliant drivers who fuel at PETRONAS on weekends
Why It’s Great: 8% cashback at PETRONAS every Saturday and Sunday, plus 1% on weekdays. No annual fee for life.
Heads-Up: Cashback is capped at RM50 per month, and the weekday rate is just 1%. Minimum income is RM5,000/month.
🔗 Apply
7. Public Bank Quantum Visa
Best For: Tap-and-go spenders
Why It’s Great: 1% cashback on every contactless transaction of RM100 or more. No annual fee for life.
Heads-Up: Cashback is capped at RM20 per month (combined with supplementary cards), and contactless payments below RM100 don’t qualify.
🔗 Apply
8. Alliance Bank Visa Virtual
Best For: Online shoppers and e-wallet users
Why It’s Great: 8x Three-Year Bonus Points for every RM1 on online shopping (including EV charging via JomCharge) and e-wallet reloads, each capped at RM3,000 spend per statement cycle. Everything else earns 1x. No annual fee for life.
Heads-Up: You earn points, not cashback, and JomPay and FPX transactions only earn 1x.
🔗 Apply
9. UOB Simple Card
Best For: People who want a no-fee backup card
Why It’s Great: 10% cashback on finance charges on purchases and cash advances when you pay at least the minimum on time. No cap and no annual fee for life.
Heads-Up: This is not a rewards card. You only get money back on interest you’ve already paid, so never carry a balance just to “earn” it.
🔗 Apply
How Much a No Annual Fee Card Saves You
| Card Type | Annual Fee | 5-Year Annual Fees |
|---|---|---|
| Free-for-life card (any card above) | RM0 | RM0 |
| Mid-tier cashback card (e.g. UOB ONE) | RM195 | RM975 |
| Premium travel card (e.g. Standard Chartered Journey) | RM600 | RM3,000 |
That’s RM975–RM3,000 kept in your pocket over five years, before first-year waivers and spend-based waivers. The RM25 yearly service tax applies to every card on top of these fees.
FAQs: What Malaysians Want to Know
Q: Is a free-for-life credit card really free?
A: You pay no annual fee, but RinggitPlus lists a RM25 service tax on each card at activation and every anniversary. Interest and late fees still apply if you don’t pay on time.
Q: What’s the difference between “free for life” and “first year free”?
A: Free for life never charges an annual fee. First year free usually charges from year two unless you hit a target. For example, the UOB ONE RM195 fee is waived only if you spend RM20,000 a year, and the RHB Shell Visa RM195 fee needs 24 swipes a year.
Q: Can I get a no annual fee card on a low salary?
A: Yes. CIMB Cash Rebate Platinum, CIMB PETRONAS Visa Platinum-i, Alliance Bank Visa Virtual and UOB Simple Card all list a RM2,000 monthly minimum income. Banks still decide based on your full profile. See our guide to credit cards for low income earners.
Q: Do no annual fee cards earn less?
A: Not always. CIMB PETRONAS Visa Platinum-i offers up to 8% at PETRONAS with no annual fee, the same headline rate as the RM240 HSBC Amanah MPower. Paid cards usually win on perks like lounge access and miles.
Cards to Approach with Caution
Some “free” cards come with strings attached:
Waiver-trap cards → The fee is “waived” only if you spend RM20,000 a year (UOB ONE) or swipe 12 to 24 times a year (Public Bank Visa Signature, RHB Shell Visa). Miss the target and you pay.
First-year-free promos → Many fee-free offers end after year one. Always check what the card costs from year two.
Interest-rebate cards → UOB Simple’s 10% rebate only pays on interest you’ve already paid. Skip it if you pay in full.
How to Apply for a No Annual Fee Credit Card in Malaysia
- Check your income eligibility (RM2k entry-level, up to RM6.7k for the more rewarding cards).
- Prepare documents: IC + payslip/EPF.
- Apply via bank or aggregator (RinggitPlus, iMoney).
- Approval can take a few working days.
Final Thoughts
A paid card has to earn its keep. A free-for-life card doesn’t.
Best simple pick: CIMB Cash Rebate Platinum (up to 5%, RM30 cap).
Best for drivers: CIMB PETRONAS Visa Platinum-i (up to 8% at PETRONAS).
Best for weekends: Maybank 2 Gold Cards (5% on weekends, RM50 cap).
Best for light travellers: RHB World Mastercard (free lounge visits, no annual fee).
Want to double your savings?
Read next: Best Cashback Credit Cards in Malaysia (Nov 2026): Top 9 Compared