Earning RM2,000 to RM3,000 a month and think a credit card is out of reach?
What if the right card paid you back on petrol, groceries and online shopping, without a heavy fee?
This guide reveals the best credit cards for low income earners in Malaysia, ranked by realistic savings and low fees. Whether you’re a fresh grad, a gig worker, or starting your first job, there’s a card here that can give you cashback every month, as long as you spend smart and pay on time.
Last checked 16 November 2026 against RinggitPlus card listings. Card terms change often, so always confirm the latest rates, caps and fees on the bank’s website before you apply. Disclosure: we may earn a commission if you apply through links on this page, at no extra cost to you.
Can You Get a Credit Card on a Low Income in Malaysia?
Yes. Under Bank Negara’s rules, new applicants need to earn at least RM24,000 a year (about RM2,000 a month). Several cards in this guide list a RM2,000 monthly minimum.
Banks still decide based on your full profile, including your credit record and employment. Meeting the minimum income doesn’t guarantee approval.
Example: Spend RM1,000 a month on a 2% card and you get RM20 back. That’s RM240 a year, tax-free.
Heads-up: according to RinggitPlus, if you earn RM36,000 a year or less, you can only hold cards from 2 banks. Pick carefully.
Top 8 Credit Cards for Low Income in Malaysia
| Rank | Credit Card | Why It’s a Good Pick | Cashback / Points | Cap | Min Income | Annual Fee | Apply |
|---|---|---|---|---|---|---|---|
| 1 | CIMB Cash Rebate Platinum | Free for life, works on everyday bills | 5% with RM3,000+ eligible spend, 2% below | RM30 | RM2,000 | Free for life | 🔗 Apply |
| 2 | CIMB PETRONAS Visa Platinum-i | Shariah-compliant fuel cashback | 4% at PETRONAS from RM500 statement balance, 8% from RM2,000 | RM50 | RM2,000 | Free for life | 🔗 Apply |
| 3 | Maybank American Express Cash Back Gold | Cashback on any amount, no minimum spend | 1% local, 1.5% overseas, unlimited | No cap | RM2,500 | RM70 (free 1st year) | 🔗 Apply |
| 4 | Hong Leong Wise | Weekend cashback from RM1,000 spend | Up to 15% weekend dining, 10% weekend petrol and groceries | RM15–RM20 per category | RM2,000 | RM98 | 🔗 Apply |
| 5 | Maybank 2 Gold Cards | Weekend cashback with no fee | 5% on weekends (Amex card) | RM50 | RM2,500 | Free for life | 🔗 Apply |
| 6 | UOB EVOL Card | Online and e-wallet cashback from RM1,000 spend | 10% online, 5% e-wallet top-ups | RM15 each | RM3,000 | RM90 (waived with 1 retail transaction a month) | 🔗 Apply |
| 7 | RHB Cash Back Visa | Low income entry, high rates if you spend more | Up to 10% on online dining and groceries with RM2,500+ monthly spend | RM10 per category | RM2,000 | RM70 (free 1st year; waived with RM10k annual spend) | 🔗 Apply |
| 8 | Alliance Bank Visa Virtual | Online and e-wallet rewards | 8x points on online shopping and e-wallet reloads | RM3,000 spend per category | RM2,000 | Free for life | 🔗 Apply |
In-Depth Reviews of the Top Picks
1. CIMB Cash Rebate Platinum
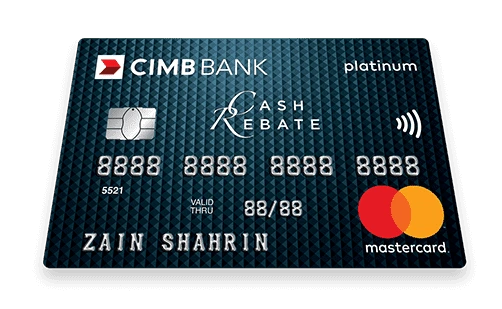
Best For: First-time cardholders who want a fee-free card for everyday bills
Why It’s Great: Up to 5% cash rebate on petrol, groceries, cinema, mobile and utility bills once your eligible spend reaches RM3,000 a month, and 2% below that. Everything else earns 0.2%. No annual fee for life.
Heads-Up: The rebate is capped at RM30 per month, and mobile and utility bills must be paid by standing instruction to count.
🔗 Apply
2. CIMB PETRONAS Visa Platinum-i
Best For: Drivers on a tight budget who want a Shariah-compliant card
Why It’s Great: 4% cashback at PETRONAS once your statement balance reaches RM500, rising to 8% at RM2,000. Groceries, dining and cashless parking earn 1% from RM500 and 2% from RM2,000. No annual fee for life.
Heads-Up: Cashback is capped at RM50 per statement cycle, and the 8% rate needs RM2,000 monthly spend, which is a stretch on a low income.
🔗 Apply
3. Maybank American Express Cash Back Gold
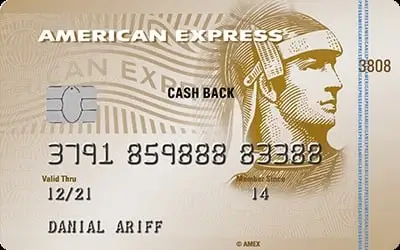
Best For: Light spenders who don’t want spend targets
Why It’s Great: Unlimited cashback on any amount: 1% on local retail spend and 1.5% on overseas spend, with no minimum spend and no cap.
Heads-Up: E-wallet reloads, JomPay and FPX payments don’t earn cashback. The RM70 annual fee is free in year one, then you need about RM7,000 of local spend a year just to cover it.
🔗 Apply
4. Hong Leong Wise
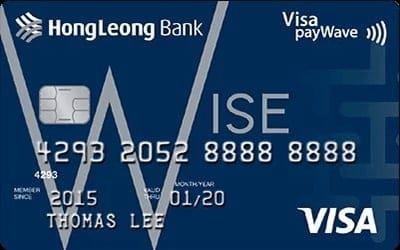
Best For: Weekend kaki makan and supermarket warriors
Why It’s Great: Up to 15% cashback on weekend dining and 10% on weekend petrol and groceries when you spend RM1,000+ a month. Weekdays earn up to 1%.
Heads-Up: Caps are RM15 per category (RM20 for dining), and spending under RM1,000 a month earns only 0.2%. The annual fee is RM98.
🔗 Apply
5. Maybank 2 Gold Cards
Best For: Weekend shoppers who want a no-fee card
Why It’s Great: You get two cards (an American Express plus a Mastercard or Visa), both with no annual fee for life. Spend any amount on weekends and earn 5% cashback with the Amex card.
Heads-Up: Cashback is capped at RM50 per month and applies to the Amex card only. Minimum income is RM2,500/month.
🔗 Apply
6. UOB EVOL Card
Best For: Online and cashless spenders earning RM3,000
Why It’s Great: 10% cashback on online spending and 5% on e-wallet top-ups when you spend RM1,000+ a month. The RM90 annual fee is waived when you make one retail transaction a month.
Heads-Up: Cashback is capped at RM15 per category (RM30 in total), and you need RM3,000 monthly income.
🔗 Apply
7. RHB Cash Back Visa
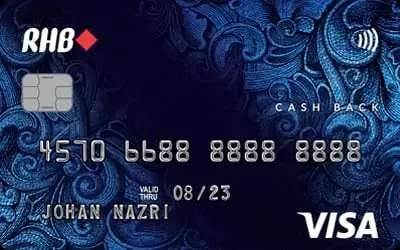
Best For: Low income earners who can ramp up their spending
Why It’s Great: 10% cashback on online dining and groceries, and 5% on petrol, dining, utilities and groceries, when you spend RM2,500+ a month. It accepts applicants from RM2,000 income.
Heads-Up: The rate drops to 2% at RM2,000 spend and 1% at RM1,000, and each category is capped at RM10 per month. The RM70 fee is free in year one and waived with RM10,000 yearly spend.
🔗 Apply
8. Alliance Bank Visa Virtual
Best For: Digital spenders who shop and top up online
Why It’s Great: 8x Three-Year Bonus Points for every RM1 on online shopping (including EV charging via JomCharge) and e-wallet reloads, each capped at RM3,000 spend per statement cycle. No annual fee for life.
Heads-Up: You earn points, not cashback, and JomPay and FPX transactions only earn 1x.
🔗 Apply
Cashback Example (RM1,000 Monthly Spend)
| Card | Spend (RM) | Cashback % | Monthly Cashback | Annual Savings |
|---|---|---|---|---|
| Maybank Amex Cash Back Gold | 1,000 (local) | 1% unlimited | RM10 | RM120 |
| CIMB Cash Rebate Platinum | 1,000 (petrol, groceries, bills) | 2% (RM30 cap) | RM20 | RM240 |
| UOB EVOL | 1,000 (RM600 online + RM400 e-wallet) | 10% and 5% (RM15 cap each) | RM30 | RM360 |
| Maybank 2 Gold Cards | 1,000 (all on weekends) | 5% (RM50 cap) | RM50 | RM600 |
That’s RM120–RM600 a year, depending on the card and how you spend. The top figure needs every ringgit spent on weekends with the Amex card.
FAQs: What Malaysians Want to Know
Q: What’s the minimum salary for a credit card in Malaysia?
A: Bank Negara requires new applicants to earn at least RM24,000 a year (about RM2,000 a month). Individual banks can set higher minimums. UOB EVOL, for example, lists RM3,000 a month.
Q: Which card is best if I only spend RM500 to RM1,000 a month?
A: Maybank American Express Cash Back Gold earns cashback on any amount with no minimum spend. UOB EVOL and Hong Leong Wise unlock their higher rates at RM1,000 monthly spend.
Q: Should I get more than one card?
A: Not at first. If you earn RM36,000 a year or less, you can only hold cards from 2 banks. Start with one card, use it for your normal spending, and pay in full every month.
Q: Can a credit card hurt me if I earn little?
A: Only if you carry a balance. RinggitPlus lists 15% p.a. interest (or profit rate) on unpaid balances for every card here, which can cancel out your cashback fast.
Cards to Approach with Caution
Some cards look great but don’t suit a small budget:
Minimum-spend traps → RHB Cash Back Visa needs RM2,500 monthly spend for its 10% rate. At RM1,000 you earn 1%.
Fee cards that eat your cashback → A RM98 or RM70 annual fee needs real spend to pay for itself. Check the maths before you apply.
Debt traps → Interest is listed at 15% p.a. on unpaid balances. Never spend money you don’t already have.
How to Apply for a Credit Card on a Low Income in Malaysia
- Check your income eligibility (RM2k entry-level, RM3k for UOB EVOL).
- Prepare documents: IC + payslip/EPF.
- Apply via bank or aggregator (RinggitPlus, iMoney).
- Approval can take a few working days.
Final Thoughts
A low income doesn’t block you from a good card. It just means you should pick fees and spend targets carefully.
Best simple pick: CIMB Cash Rebate Platinum (free for life, up to 5%).
Best no-minimum-spend pick: Maybank Amex Cash Back Gold (1% on any amount).
Best for weekends: Maybank 2 Gold Cards (5% on weekends, RM50 cap).
Best for online spenders: UOB EVOL (10% online, 5% e-wallet).
Earning a bit more?
Read next: How to Choose a Credit Card When You Earn RM3,000-RM5,000 in Malaysia
Want zero fees?
Read next: Best No Annual Fee Credit Cards in Malaysia 2026